Open visual reader →
When demand falls, which costs move with it?
Compare reported cost adjustment with revenue collapse, then identify the contract and cash evidence needed for capacity decisions.
Explore Ryanair →
The question
When demand falls, which costs move with it?
Consolidated IFRS operating totals; pandemic shock and later recovery · Financial years ended March 31, 2020–2024. When contribution falls and committed operating costs adjust more slowly, operating profit falls faster than revenue; the sensitivity depends on the current scale, cost behavior and horizon.
Mechanism 1 · Capacity reduction has a restart cost
Capacity reduction has a restart cost
After FY2021, the capacity question is difficult even for a low-cost airline: which costs can be removed without losing the ability to restart? Ryanair’s contemporaneous chairman’s report describes pandemic restrictions, cost reductions, cash preservation and payroll support. It also describes retaining operational readiness. This is management’s account of the trade-off, not proof that each action was optimal. [Annual Report FY2021, pp. 3–5](https://investor.ryanair.com/wp-content/uploads/2021/07/Ryanair-Holdings-plc-Annual-Report-FY21.pdf).
- Ryanair Holdings plc Annual Report 2024 — PDF index 67 (printed p. 65), Selected Financial Data: Total operating revenues, Total operating expenses, Operating profit/(loss), euro columns FY2020–FY2024. PDF indexes 118–119 (printed pp. 116–117), FY2024 versus FY2023 cost review. PDF index 188 (printed p. 186), government payroll supports.
- Ryanair Holdings plc Annual Report FY2021 — Printed pp. 3–5, Chairman’s and CEO’s reports: pandemic restrictions, cost reduction, cash preservation, payroll support and readiness to resume service.
Mechanism 1 · Capacity reduction has a restart cost
Revenue and expenses fell at different rates
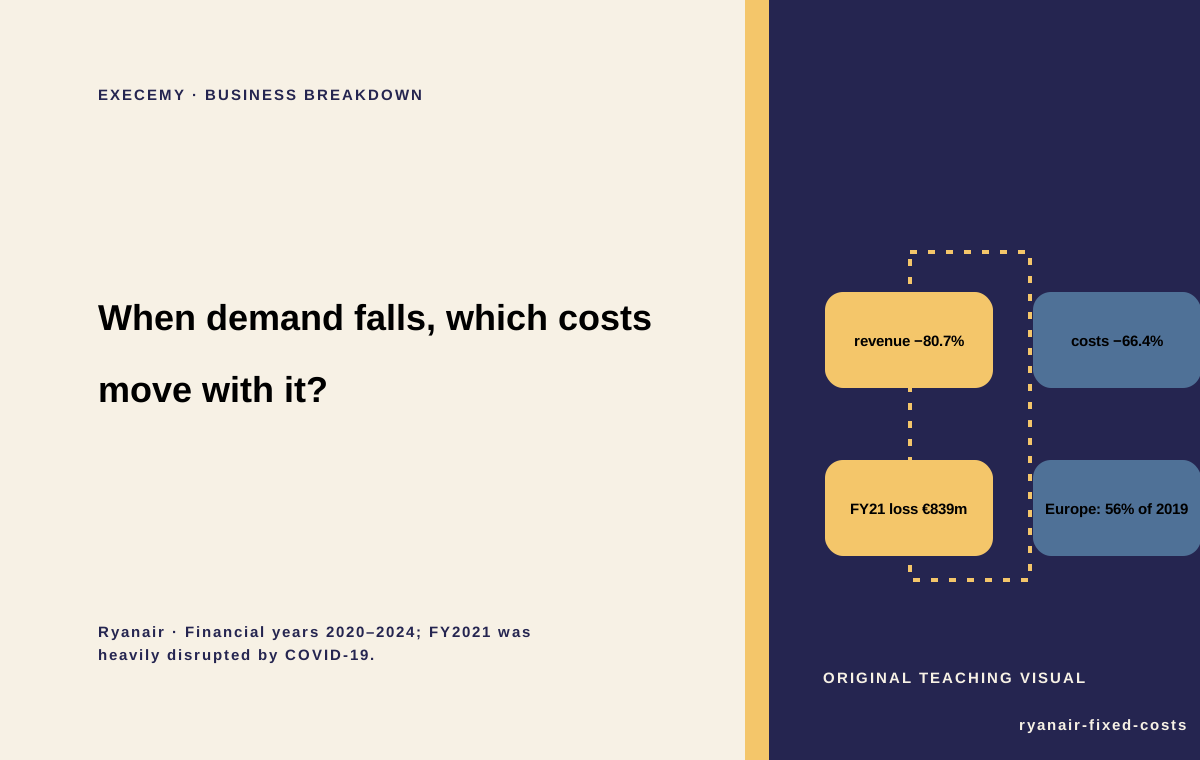
Ryanair’s FY2024 Selected Financial Data table reports FY2020 revenue of €8,494.8 million and expenses of €7,367.4 million, followed by FY2021 revenue of €1,635.8 million and expenses of €2,475.2 million. Revenue fell 80.7%; expenses fell 66.4%. FY2021’s operating result was a €839.4 million loss. All years end March 31, and FY2020 already includes the early pandemic. [Selected Financial Data, euro columns](https://investor.ryanair.com/wp-content/uploads/2024/06/Ryanair-2024-Annual-Report.pdf).
- Ryanair Holdings plc Annual Report 2024 — PDF index 67 (printed p. 65), Selected Financial Data: Total operating revenues, Total operating expenses, Operating profit/(loss), euro columns FY2020–FY2024. PDF indexes 118–119 (printed pp. 116–117), FY2024 versus FY2023 cost review. PDF index 188 (printed p. 186), government payroll supports.
- Ryanair Holdings plc Annual Report FY2021 — Printed pp. 3–5, Chairman’s and CEO’s reports: pandemic restrictions, cost reduction, cash preservation, payroll support and readiness to resume service.
Mechanism 2 · Expense categories do not reveal avoidability
Expense categories do not reveal avoidability
An aircraft’s accounting depreciation, a lease cash payment, fuel needed for a flight, staff readiness and maintenance obligations can have different adjustment patterns. Categories are starting points for contract and operating review. It would be an error to classify all staff as variable, all ownership expense as current cash, or all non-fuel expense as fixed merely because the public table groups them that way.
- Ryanair Holdings plc Annual Report 2024 — PDF index 67 (printed p. 65), Selected Financial Data: Total operating revenues, Total operating expenses, Operating profit/(loss), euro columns FY2020–FY2024. PDF indexes 118–119 (printed pp. 116–117), FY2024 versus FY2023 cost review. PDF index 188 (printed p. 186), government payroll supports.
- Ryanair Holdings plc Annual Report FY2021 — Printed pp. 3–5, Chairman’s and CEO’s reports: pandemic restrictions, cost reduction, cash preservation, payroll support and readiness to resume service.
Mechanism 2 · Expense categories do not reveal avoidability
A restart needs incremental cash evidence
For a flight restart, compare incremental expected fare and ancillary revenue with fuel, airport, handling and other genuinely incremental costs, including the capacity and staffing required. A fully allocated annual loss may not decide whether that flight adds cash. For retaining the whole fleet, the horizon is longer: financing, maintenance, asset values and demand scenarios become central. A contribution-positive flight and an unsustainable balance sheet can coexist.
- Ryanair Holdings plc Annual Report 2024 — PDF index 67 (printed p. 65), Selected Financial Data: Total operating revenues, Total operating expenses, Operating profit/(loss), euro columns FY2020–FY2024. PDF indexes 118–119 (printed pp. 116–117), FY2024 versus FY2023 cost review. PDF index 188 (printed p. 186), government payroll supports.
- Ryanair Holdings plc Annual Report FY2021 — Printed pp. 3–5, Chairman’s and CEO’s reports: pandemic restrictions, cost reduction, cash preservation, payroll support and readiness to resume service.
Mechanism 3 · A recovery year changes more than volume
A recovery year changes more than volume
Recovery does not resolve the attribution problem. The FY2024 financial review links changes in costs and earnings to traffic, fares and fuel prices; it is not a claim that every extra revenue euro flowed through an unchanged cost base. Higher prices can reduce an expense share even when the expense amount rises. [FY2024 financial review, printed pp. 116–117](https://investor.ryanair.com/wp-content/uploads/2024/06/Ryanair-2024-Annual-Report.pdf).
- Ryanair Holdings plc Annual Report 2024 — PDF index 67 (printed p. 65), Selected Financial Data: Total operating revenues, Total operating expenses, Operating profit/(loss), euro columns FY2020–FY2024. PDF indexes 118–119 (printed pp. 116–117), FY2024 versus FY2023 cost review. PDF index 188 (printed p. 186), government payroll supports.
- Ryanair Holdings plc Annual Report FY2021 — Printed pp. 3–5, Chairman’s and CEO’s reports: pandemic restrictions, cost reduction, cash preservation, payroll support and readiness to resume service.
Optional application · unscored
Cancel a seasonal route?
A fictional airline evaluates cancelling a route for a season.
Reveal: Compare avoidable cash costs, notice periods, alternative aircraft use and restart costs; an allocated annual margin cannot decide the route alone.
Teaching assumption: Fictional route; no measured Ryanair route economics implied.
The answer
The relevant risk is how fast costs can adjust without losing needed capability.
When contribution falls and committed operating costs adjust more slowly, operating profit falls faster than revenue; the sensitivity depends on the current scale, cost behavior and horizon. Ryanair’s annual change combines restrictions, capacity changes, fares, fuel and support measures. Fixed-cost exposure is relevant but not separately identified. Reported expenses fell substantially during the shock; the cost base was not entirely fixed. Later cost shares also moved with fares and fuel prices. The case is bounded to Consolidated IFRS operating totals; pandemic shock and later recovery during Financial years ended March 31, 2020–2024.
Sources and limitations
- Ryanair Holdings plc Annual Report 2024 — Ryanair Holdings plc
PDF index 67 (printed p. 65), Selected Financial Data: Total operating revenues, Total operating expenses, Operating profit/(loss), euro columns FY2020–FY2024. PDF indexes 118–119 (printed pp. 116–117), FY2024 versus FY2023 cost review. PDF index 188 (printed p. 186), government payroll supports.
Precise uses are bound in the claim ledger.
Financial years end March 31. FY2020 includes early pandemic effects. Expense totals do not identify variable cost, avoidability, cash obligations, or route-level contribution. Do not use adjacent USD translation column.
- Ryanair Holdings plc Annual Report FY2021 — Ryanair Holdings plc
Printed pp. 3–5, Chairman’s and CEO’s reports: pandemic restrictions, cost reduction, cash preservation, payroll support and readiness to resume service.
Precise uses are bound in the claim ledger.
Contemporaneous management account; no causal isolation or fixed/variable schedule. Quantitative exhibit uses FY2024 Selected Financial Data euro columns, not mixed rounded highlights.
Original illustrative scenes are not documentary evidence.
New concepts and cases by email